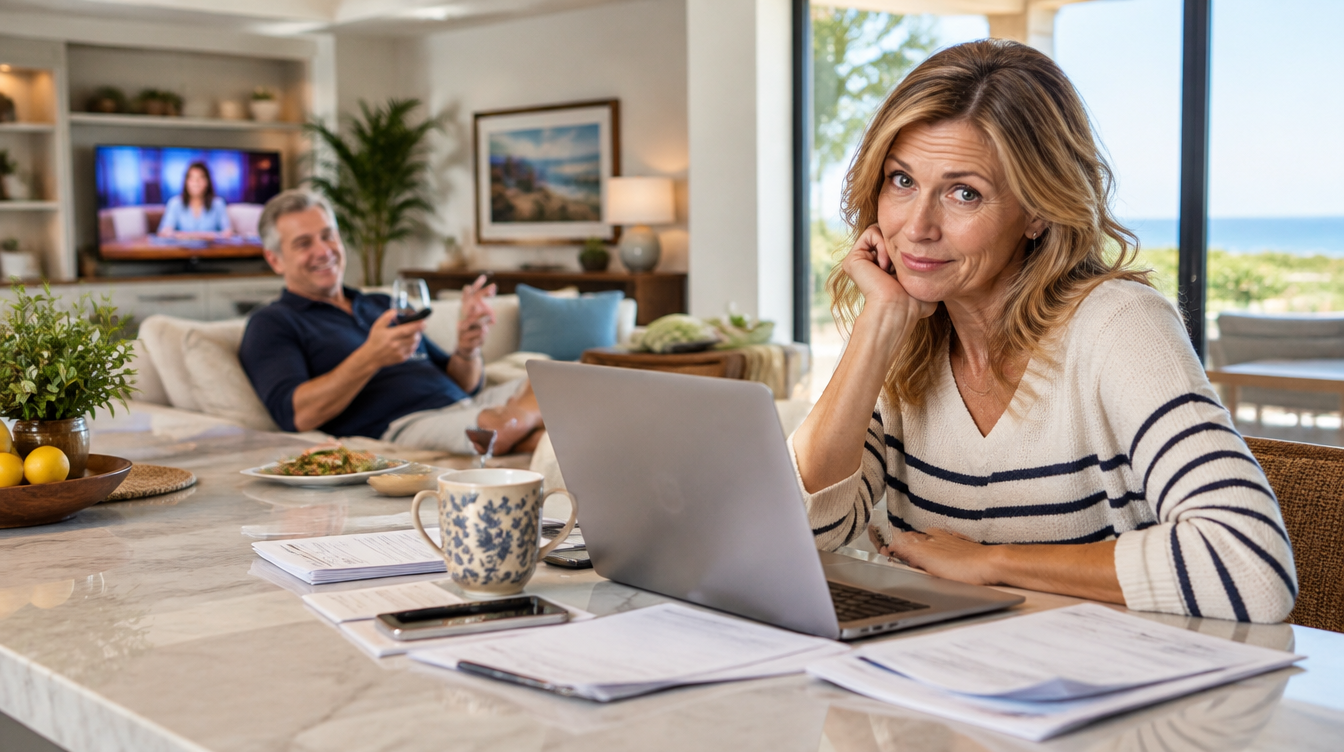
He spent 40 years dreaming about retirement. She wasn’t expecting to become his lunch companion, social calendar and unpaid activities director. But something bigger is going on here: when one spouse retires, the whole household economy changes. And almost nobody puts that in the retirement calculator.
There’s an old saying: “I married you for better or worse, but not for lunch.”
I understand that one a little better than I used to.
When my husband retired, he suddenly had a lot more time. Long lunches sounded wonderful. Preferably with a nice bottle of wine … or two. He enjoyed watching political television, often at a volume that suggested he wanted to participate in the argument personally.
And he wanted company.
Meanwhile, I was still raising our son, running a household and living a life that hadn’t suddenly cleared its calendar.
He had retired from his job. I hadn’t retired from mine. Except somehow, mine had gotten bigger.
There were more meals to think about, more shared time to arrange and a surprising amount of new attention being paid to what we were spending. And when someone who used to be busy all day suddenly has an empty schedule, the other person can quietly become the schedule.
I know plenty of couples who absolutely love retirement together. They travel, golf, volunteer, pursue their own interests and meet up for dinner with actual things to talk about.
But I’ve also watched couples discover that the person they love spending weekends with isn’t necessarily someone they want to spend every single Tuesday with.
And here’s what I find fascinating. We spend decades planning how much money we’ll need to retire. We calculate investments, Social Security, healthcare, inflation and how long our savings might last.
But who calculates the value of the other person’s time? Or what happens when one person retires and the other suddenly picks up a brand new full time job?
Because retirement doesn’t just change the paycheck. It can change who’s doing the work, who’s spending the money and who gets to decide how the days are spent.
Retirement Doesn’t Give You a New Marriage. It Increases the Dosage.
Here’s a little math nobody does at the retirement party.
For most of a working marriage, a couple spends a few waking hours together on weekdays, plus weekends. Breakfast, maybe. Dinner. A show. Bed. Then the whole thing resets.
Now one person retires. Suddenly there are roughly 40 to 50 extra waking hours a week that used to be filled by an office, a commute, colleagues and a boss. And many of those hours now happen in the same house as you.
That’s rough math, not a study. But think about what it means. Your marriage didn’t change. You just went from a few doses a day to a continuous drip.
If your relationship is wonderful, more of it can be wonderful. If there were little irritations you used to manage in small amounts, like the TV volume, the opinions about the dishwasher or the way he narrates the news, they now arrive in industrial quantities.
Retirement doesn’t change who you married. It just turns up the volume. Sometimes literally.
Apparently, There’s a Name for This
I assumed the whole “retired husband underfoot” thing was just something women joked about over salads.
Turns out it has a name: retired husband syndrome. I did not make that up.
The term was coined in Japan in the 1990s by a doctor who noticed his female patients developing stress symptoms after their husbands retired. And Japan has an even better nickname for the husbands themselves: “nure ochiba,” or wet fallen leaves. As in, the kind that stick to the bottom of your shoe and simply will not come off.
I have never heard anything more poetic or more savage.
The research is real. A Japanese study published in 2021 followed 3,794 women whose husbands retired. Researchers found a small bump in the wives’ psychological distress during the first few years, although it generally faded. Women with active social lives and good relationships with their husbands came through it best.
An earlier study made the point even sharper. Its title was “Pappa Ante Portas,” borrowed from a famous 1991 German comedy about a retired husband who drives his wife to the edge of sanity. (Researchers do occasionally have a sense of humor.) It found that a husband’s earlier retirement was linked not only to more stress for his wife, but also to tighter household finances, and that the money strain explained part of the effect.
Now, Japan isn’t America, and a couple of studies don’t mean every retired husband is a walking household disruption. But they confirm something I’ve always suspected: retirement isn’t just a huge life change for the person leaving work. It’s a huge life change for the person married to them.
Nobody Gives the Spouse an Onboarding Packet
Think about how companies handle a big transition. A new hire gets an orientation, a manual, a list of responsibilities and someone to explain where the good coffee is. A retiring employee gets a party, a plaque and a cake that says “Enjoy Your Freedom!”
The spouse at home gets… nothing. No orientation. No updated job description. No meeting about who now handles lunch. Just a new coworker who has opinions about how you load the dishwasher and no scheduled meetings until approximately never.
And that’s the core problem. Retirement planning treats the household like it has one employee. It has two.
The Retirement Calculator Has Never Met Your Wife
Open almost any retirement calculator and it asks the same questions. How old are you? How much have you saved? When do you want to retire? How much income will you need?
All very reasonable. But I’ve never seen one ask, “How many extra hours of work will your spouse be doing once you’re home?” Or “Does your husband have anyone besides you to go to lunch with?” Or my personal favorite: “Who is going to figure out what we’re doing all day?”
Those questions matter, because time is money. If one person retires and suddenly needs more help planning meals, activities, errands and decisions, someone is providing that help. Usually for free. And if the other spouse is still working, raising a child or juggling her own responsibilities, that time comes out of something: her job, her friends, her workouts, her hobbies, or the occasional glorious afternoon when nobody asks where the good scissors are.
We’re very good at putting a dollar value on paid work. We’re remarkably casual about treating someone’s unpaid time as free.
The Unpaid Labor Nobody Puts on the Balance Sheet
According to the U.S. Bureau of Labor Statistics, in 2025 women spent an average of 2.4 hours a day on household activities, compared with 1.6 hours for men.
That’s all American adults, not specifically retired couples, so it doesn’t prove retired husbands create more work. But it shows the habits many couples carry into retirement. Women still do more of the daily domestic work, and a retirement party doesn’t erase 30 or 40 years of patterns.
If she’s always been the one who plans meals, remembers birthdays, books appointments and knows when the fridge needs cleaning, there’s no reason that work disappears when he stops getting a paycheck. In fact, another person home all day can create more of it. More dishes. More meals. More decisions. More interruptions. And sometimes more supervising of someone’s sudden enthusiasm for reorganizing a pantry that was perfectly organized yesterday.
Let’s put a pretend price tag on it. Say a spouse picks up just five extra hours a week of household management and companionship duties after the other retires. At an illustrative $25 an hour, that’s $125 a week, or about $6,500 a year in unpaid time.
Nobody’s sending an invoice, and this isn’t an estimate of what retired husbands typically “cost.” It’s just a way of showing that time has value even when no check gets written. Now stretch that over 10 or 15 years of retirement. Suddenly, who does what around the house looks a lot less like a squabble and a lot more like financial planning.
Retirement Can Be Surprisingly Expensive When Everyone’s Home
The classic assumption is that expenses drop in retirement. No commute. Fewer work clothes. No more office lunches. Wonderful.
But you also now have a person with 40 extra hours a week to fill. And depending on how they fill them, those hours can get pricey. Long lunches. Golf. Travel. More entertaining. Home projects. Online shopping. Subscriptions. New hobbies with very expensive new equipment. Or simply a lot more meals at home, which someone has to plan.
To be fair, spending doesn’t only go up. Research published in 2026 by retirement economist David Blanchett found that inflation adjusted spending often declines over the course of retirement, even among fairly comfortable retirees.
But spending less over 25 years is very different from assuming year one will be cheaper. Picture a couple who starts having two extra restaurant lunches a week at $90 each, including tax and tip. That’s $9,360 a year. And that’s before anyone orders the second bottle of wine. Which, in my experience, someone always does.
It’s a made up number. Plenty of couples spend less, and plenty happily spend more. The point is that retirement changes how money gets spent, and those changes deserve their own line in the budget, ideally before Tuesday lunch becomes a standing reservation.
When the Paycheck Stops, Does the Micromanaging Start?
This is the uncomfortable part, but it’s an important one.
In my experience, my husband’s retirement brought a lot more attention to our household finances. Not because anything was suddenly dire. There was simply more time to think about the money, and more time to question what was being spent.
When someone has spent decades making decisions, managing people, solving problems or running a business, retirement leaves a big hole in the day. And it’s easy for some of that energy to get redirected toward the household. The grocery bill. The credit card statement. What dinner cost. Whether the landscaper really needed to come this week.
Think of it as the CEO who lost his company and found a new one: yours.
To be fair, research doesn’t show that retired executives universally turn into household accountants. Some couples become much better financial partners after retirement, because they finally have time to plan together. Others discover they never actually agreed on how money should be managed in the first place.
The problem isn’t checking the finances. It’s when checking turns into policing, and one spouse suddenly has to justify purchases that were never an issue before. There’s a world of difference between two people reviewing a retirement budget together and one person announcing that the household now requires approval for a $40 purchase.
Retirement may change the family income. It shouldn’t change who gets a say in spending it.
And if financial “oversight” ever turns into intimidation, isolation or cutting off someone’s access to money, that’s far more serious than a budgeting disagreement. The goal is transparency and shared decisions, not one partner taking on a brand new unpaid job as the other’s financial supervisor.
The Age Gap Nobody Thought About at the Wedding
Here’s a complication that rarely comes up: couples don’t always retire at the same time.
He may be 67 and done. She may be 55, still building her career, still raising a teenager, or simply not remotely interested in retiring. Yet once one person is home, there’s often an assumption that the couple is “entering retirement together.” They’re not. They’re entering two completely different stages of life under the same roof. One of them is on vacation. The other one is still at work, just with a new coworker.
And the money can get serious. Take health insurance. Medicare generally starts at 65. If your husband retires at 66 and you’re 57 and covered through his employer’s plan, you may need another source of coverage for eight years. Depending on your options, that can be a major expense.
Or say one spouse decides to cut back on work to spend more time with the newly retired partner. Lovely idea. But giving up five years of earnings isn’t just giving up five paychecks. It can also mean fewer retirement contributions, less time for investments to grow, a smaller Social Security benefit and less access to employer benefits.
None of that makes retiring together a bad idea. It means the decision deserves real math, made by both people. Because “I’d love for you to retire too” is a romantic sentence. It is not a financial plan.
Social Security Is a Marriage Decision, Not a Birthday Decision
Here’s a conversation that’s less exciting than picking a cruise but a lot more important: when should each of you claim Social Security?
Many people fixate on the earliest age they qualify, usually 62, and how much they’ll get each month. But married couples need to look at the whole household. A higher earner who waits to claim can increase their monthly benefit, up to age 70. That matters not just while you’re both alive, but for the benefit a surviving spouse may receive later.
The right answer depends on each person’s earnings, age and situation, and waiting isn’t automatically right for everyone. But it’s worth thinking about the spouse who may someday be living on one income instead of two. As someone who’s been on the other side of that, I can tell you it’s a conversation worth having while you’re both still sitting at the same table.
And here’s a detail people miss: if you claim benefits before full retirement age and keep working, Social Security may temporarily hold back part of your payments once you earn above certain limits. That matters if retirement turns out to be less fun, or more expensive, than expected and someone decides to go back to work.
Nobody wants to interrupt a retirement party to talk about survivor benefits. But the consequences last a lot longer than the cake.
When He Retires, You May Become His Entire Social Life
His company. His conversation. His reason to get dressed and leave the house. His standing lunch date. His entertainment on a perfectly ordinary Wednesday.
This is where a lot of couples hit trouble without understanding why. For years, work quietly supplied most of one partner’s routine and social life: colleagues, meetings, clients, a reason to leave the house, people who expected things from him. Then retirement arrives and all of it disappears almost overnight. It’s like losing your entire friend group, your schedule and your sense of purpose in a single afternoon, with cake.
Meanwhile, his wife may already have a full life of friends, activities, family and interests. Naturally, he wants to spend time with her. And just as naturally, she may not want to rebuild her entire life around entertaining him.
Neither person is being selfish. One person’s social world just disappeared while the other’s was still running perfectly well. Research on retired couples suggests that the quality of the marriage and each partner’s own social connections both shape how well they adjust.
And here’s where money comes back in. An independent social life can cost something: golf memberships, classes, clubs, community activities, travel. But depending entirely on your spouse’s time costs something too. It’s just paid in a currency nobody tracks: hours. And occasionally, patience.
So maybe the retirement budget needs a line item for having a life that doesn’t require your partner to be part of every minute of it. Not because you don’t love each other. Because having something interesting to talk about at dinner is rather nice.
Isn’t Retirement Supposed to Be Relaxing for the Brain?
What happens when work was someone’s main source of mental stimulation?
The research is more nuanced than “retirement rots your brain.” Reviews of long term studies have found little overall link between retirement and general cognitive decline, with mixed results for memory. Leaving a stressful job can even be good for you. And leaving work doesn’t mean leaving stimulation behind. Someone who spends retirement learning a language, volunteering, traveling, gardening, mentoring or running interesting projects may be busier, mentally, than ever.
Someone else may find every day starts to look exactly like the last one. The key question isn’t whether someone still has a job. It’s what replaces the job.
An afternoon of political TV doesn’t mean someone is losing their mind. Although it may cost the rest of the household a little of theirs. But it’s worth planning how retirement will provide structure, learning, people and purpose. Because if you haven’t thought about what you’re retiring to, having nothing to do can get surprisingly expensive. For you, and for whoever you live with.
The Retirement Budget Needs Two Columns: His and Hers
Here’s something I wish every financial planner did. Before a couple retires, ask each person to describe an ordinary Tuesday. Not the month in Italy. A completely normal Tuesday, six months into retirement.
What time do you wake up? What are you doing at 10 a.m.? Who makes lunch? How often are you eating out? What do you do separately? What do you want to do together? How much are you planning to spend? And who’s handling the errands, bills, appointments, shopping and meals?
I suspect a lot of couples would discover their Tuesdays look wildly different. He imagines long, leisurely lunches and spending every afternoon together. She imagines finally having time for her own friends, interests or business. Neither is wrong. But those two Tuesdays won’t coexist very well unless someone notices the difference before retirement starts.
I’d also give each spouse their own discretionary budget: money they can spend without having to defend every purchase. And I’d spell out household responsibilities. If both people are now home, why should the person who’s run the house for 30 years automatically keep doing everything?
Retirement is a chance to renegotiate the deal. Not just carry the old one forward with more people in the kitchen.
Maybe the Real Retirement Plan Is a Merger Agreement
Think about it. A marriage is already a small economic partnership. There are assets, expenses, responsibilities, shared goals and individual interests. Sometimes even staff, if you count the gardener and the guy who fixes the air conditioning.
Then one partner retires. The household loses an income stream, gains an enormous amount of free time and may completely change how decisions get made. In any other business, we’d call that a major restructuring. There would be meetings. Spreadsheets. A very serious PowerPoint. Everyone would know their new role.
At home, we usually just assume it’ll work itself out. Sometimes it does. Other times, one partner gets a breezy new schedule while the other quietly becomes the unpaid operations department.
Couples would be so much better off treating retirement as something they design together. Not a reward one person receives while the other adjusts around it. And not a financial finish line where the only question is whether the portfolio is big enough.
The real question is whether the life you’ve planned actually works for both people who have to live it.
THE SEPTEMBER TAKE
My husband retired from work, but our household didn’t retire with him. And I think that’s the part traditional retirement planning misses completely.
We calculate what happens when the paycheck stops. We almost never calculate what happens when the dosage of marriage triples overnight, or who quietly picks up the extra work when someone’s home all day.
A successful retirement shouldn’t require one person to give up her independence so the other can enjoy his. Write the onboarding packet. Renegotiate the job descriptions. Budget for separate lives as well as shared ones.
Better or worse, absolutely. But lunch every single day? That deserves its own planning session.
Plan the money. Then plan the Tuesdays.
Do This Week
1. Have the Tuesday conversation.
Ask your partner what an ordinary weekday in retirement actually looks like. Not the vacation version. The regular, slightly boring version. You may be surprised how different your answers are.
2. Write the onboarding packet.
Make a simple list of every household job: meals, shopping, appointments, bills, errands, social plans. Then decide together who owns what once both people are home.
3. Make two retirement budgets.
One for the essentials, and one for the lifestyle you actually want. Include lunches, travel, hobbies, memberships and everything else that will fill all those new hours.
4. Give each person some financial independence.
Agree on an amount each spouse can spend without needing approval. The number will vary by household. The principle is that both people get a voice.
5. Run the healthcare numbers before anyone leaves work.
If one spouse is under 65, find out what insurance will cost and how coverage changes. Don’t assume Medicare or retiree benefits will automatically cover both of you.
6. Review Social Security as a couple.
Look at each person’s claiming age, spousal and survivor benefits, and how part time work could affect payments before full retirement age. A qualified financial planner can help compare options.
7. Budget for separate lives, too.
You need a shared life. You don’t need a shared calendar for every hour of it. Your own friends and interests are worth planning and paying for.
September Wellness provides educational information about retirement finances, household economics and relationships. Financial situations, Social Security benefits, healthcare coverage and retirement decisions vary by household. The examples in this article are illustrative and are not estimates of typical retirement costs. Consult qualified financial, tax or benefits professionals before making significant retirement decisions.
Sources & Further Reading
1. Oshio, T. What Factors Affect the Evolution of the Wife’s Mental Health After the Husband’s Retirement? Evidence From a Population-Based Nationwide Survey in Japan. Journal of Epidemiology, 2021. Follows 3,794 women whose husbands retired, finding a modest, mostly temporary rise in distress.
2. Bertoni, M., and Brunello, G. Pappa Ante Portas: The Effect of the Husband’s Retirement on the Wife’s Mental Health in Japan. Social Science & Medicine, 2017. Examines how husbands’ retirement affected wives’ well-being and household finances.
3. U.S. Bureau of Labor Statistics. American Time Use Survey — 2025 Results. BLS, 2026. Shows how men and women divide their time among paid work, household activities, care and leisure.
4. Blanchett, D. How Spending Evolves in Retirement: A Smile, a Smirk, or Something Else?. Financial Planning Review, 2026. Examines how household spending changes over the course of retirement, including the tendency for inflation-adjusted spending to decline over time.
5. Social Security Administration. Do You Qualify for Social Security Spouse’s Benefits?. SSA, 2024. Explains spousal benefit eligibility and why each partner’s claiming decisions matter.
6. Social Security Administration. What You Should Know About Social Security if Your Spouse Passes Away. SSA, 2025. Discusses survivor benefits and why couples should consider the surviving spouse when planning retirement income.
7. Social Security Administration. What Happens if I Work and Get Social Security Retirement Benefits?. SSA, 2026. Explains how employment earnings can affect retirement benefits before full retirement age.
8. Centers for Medicare & Medicaid Services. Retiree Insurance and Medicare. Medicare.gov. Explains how retiree coverage interacts with Medicare and why couples retiring at different ages need to review their health insurance.
9. The Effects of Retirement on Cognitive Functioning Based on a Systematic Review of Longitudinal Studies. Health Psychology Review, 2025. Reviews 22 longitudinal studies examining retirement and later cognitive functioning.
10. Effect of Retirement on Cognitive Function: A Systematic Review and Meta-Analysis. Occupational and Environmental Medicine, 2021. Finds little overall association between retirement and global cognitive performance, with more mixed findings for memory.